480.628.1128 homes@brittanyfanelli.com Instagram @brittanyfanelli_homes
Schedule a consultation

First-Time Home Buyers in the East ValleyYour first home, one calm step at a time.


Buying your first home is exciting, and it can feel like a lot. I'll explain each step before we reach it, so you'll know what's next, with no pressure from me.

Start here

Questions are part of the process

Every first-time buyer arrives with questions, and there's no such thing as a small one. This page gathers the worries first-time buyers share most and what I do about each one, the Arizona steps from our first sit-down to your keys, and the programs worth asking about. Read it at your own pace.

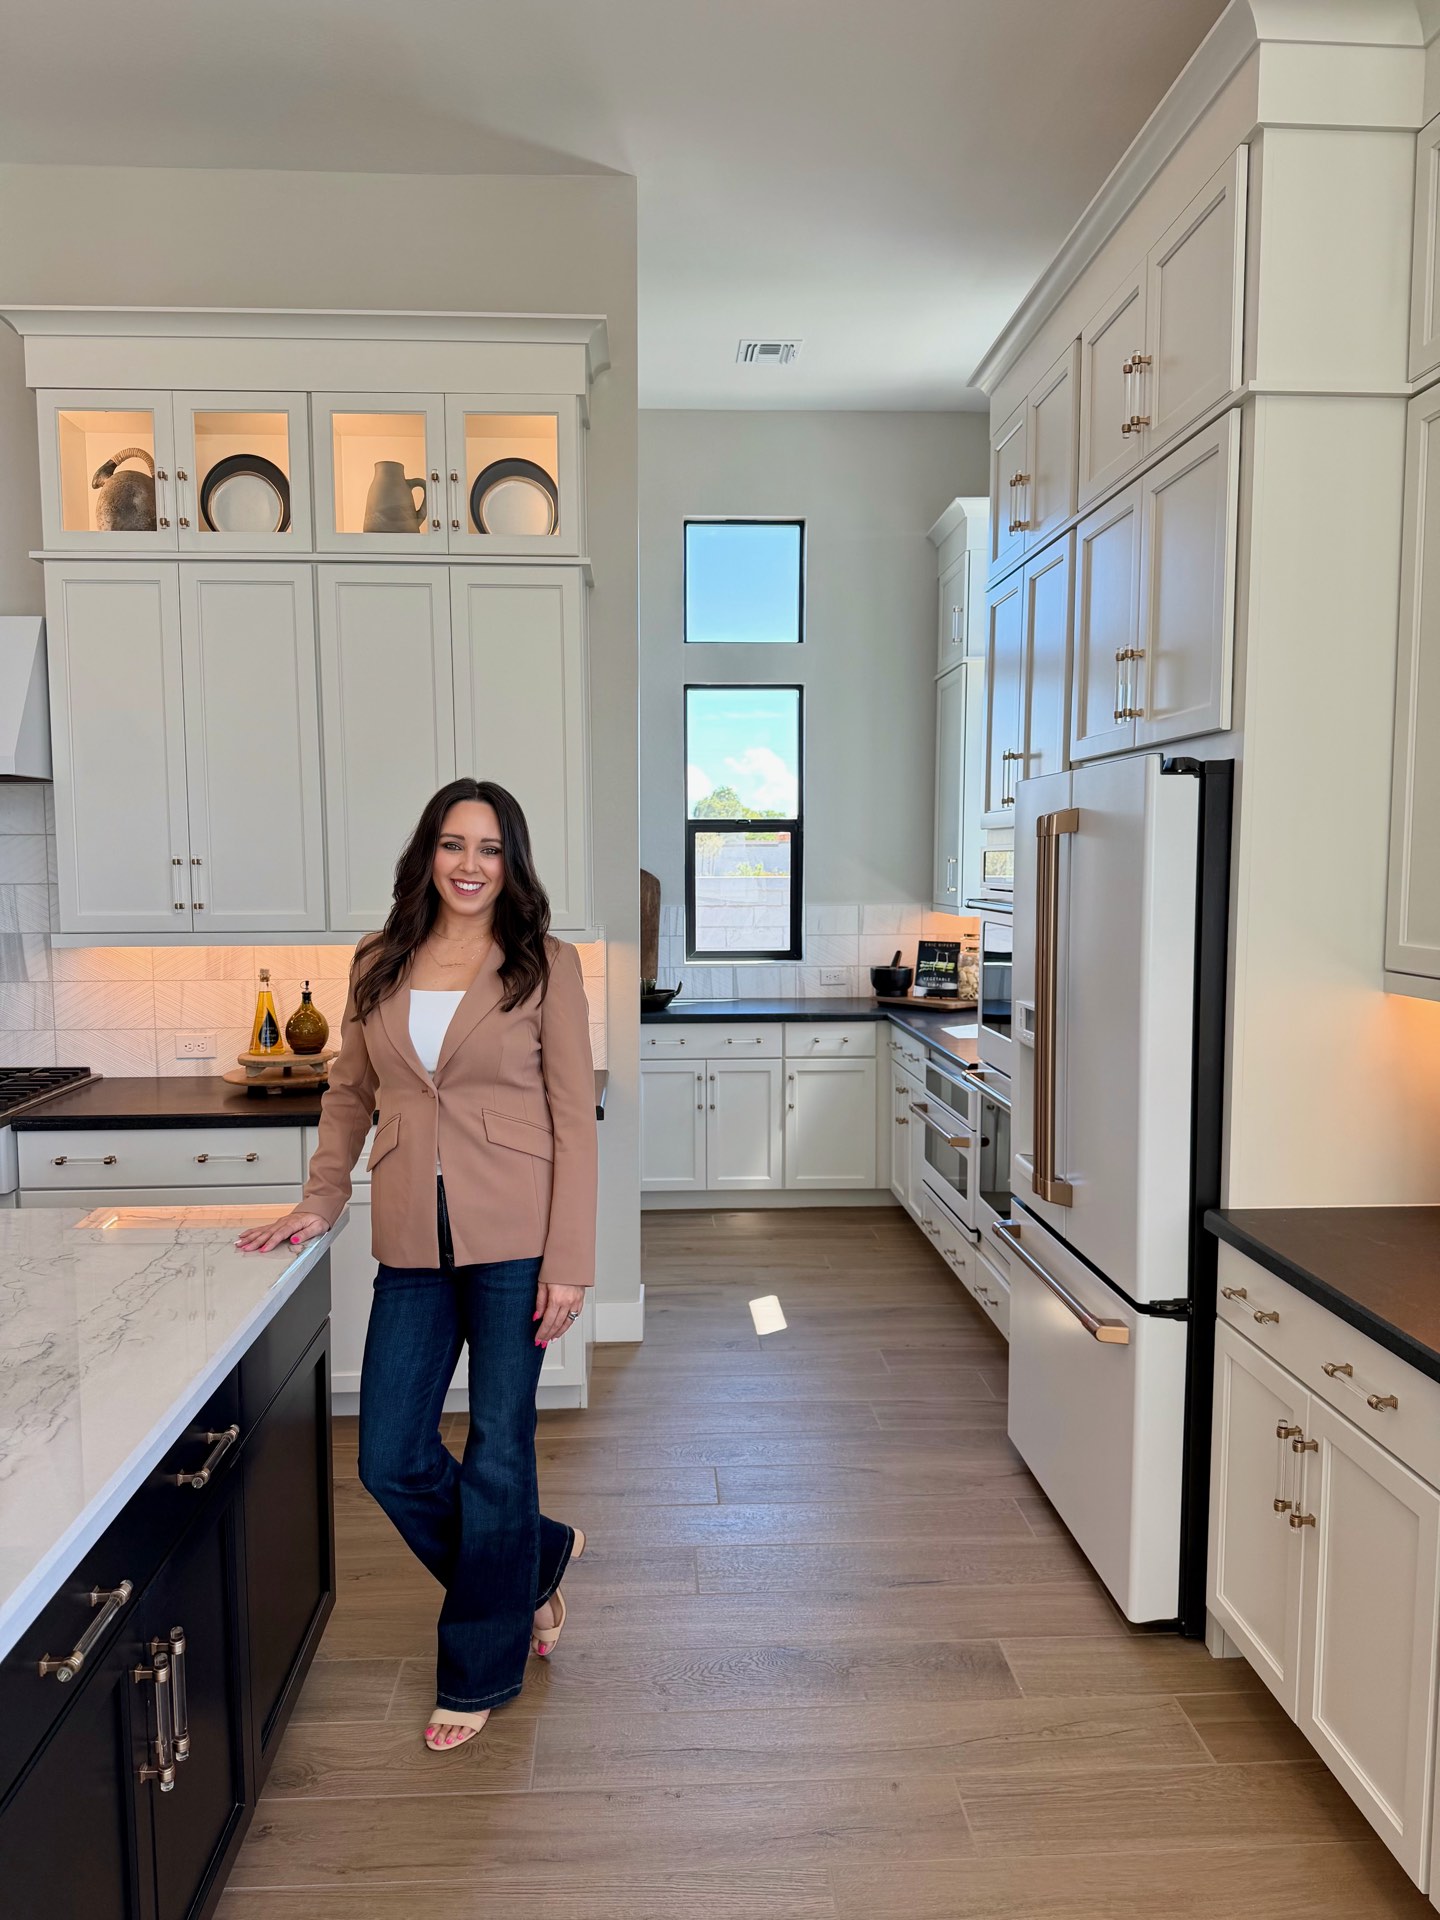
Brittany Fanelli, REALTOR®, standing in a bright white kitchen
My first home

I've been where you are


I bought my first home at 19, and I felt much the way many first-time buyers do today. I love homes and the details that make them.

Before real estate, I spent several years in a surgical office, much of that time in management. Guiding patients through health decisions is a lot like guiding clients through home decisions: you listen closely, explain clearly and make sure no one feels alone in it.

Here is how that shows up when we work together.

01

Every step explained first

Before we reach each stage, I'll walk you through what happens, why it matters and what you'll decide.

02

Every date in writing

The day your offer is accepted, you'll have a key-dates page, so you can see what's done, what's next and what's due.

03

Your pace, no pressure

You set the pace of the search, and every question is welcome. Once we're under contract, I'll make sure you see each deadline coming.

04

The details, noticed

I'm extremely detail oriented. On every tour, I'll point out the little things that are easy to miss.

If it feels like a lot

You're in good company


Among first-time buyers in recent national surveys:

  • 38%Named understanding the steps and process as one of the hardest partsNAR, 2025 Profile of Home Buyers and Sellers, Nov 2025
  • 49%Felt they lost control of the process at some pointBest Interest Financial & Clever Real Estate, survey of recent buyers, Mar 2026 (28% of repeat buyers)
  • 76%Said their agent helped them understand the processNAR, 2025 Profile of Home Buyers and Sellers, Nov 2025

Feeling unsure the first time is normal. It gets easier one step at a time.

What first-time buyers worry about most

Eight common worries, and how I help

These concerns come up again and again in national surveys of first-time and aspiring buyers. Each one is reasonable, and each one gets easier with a plan.

“Can I really afford this?”

Home prices and the monthly payment top most surveys of first-time buyers.

How I help: we weigh a home's full monthly cost, with taxes, insurance and any HOA dues, not just its price. Try my calculators with your own numbers, then a licensed lender gives you real ones. Before any offer, I pull the actual tax bill and HOA dues.

“How much do I need to save?”

Many buyers assume they need more up front than some loan programs require.

How I help: we get you real answers early, from a licensed lender who can explain your loan options and the down payment assistance programs available in Arizona. Your offer can also ask the seller for credits toward closing costs.

“I don't know how any of this works.”

After finding the right home, understanding the steps is one of the hardest parts for first-time buyers: 38% named it in NAR's 2025 survey.

How I help: we take the steps in the order you'll meet them, and you'll have the whole path and every contract date in writing. No question is too basic, and the words you'll hear are defined below.

“What about the costs nobody mentions?”

Closing costs, early repairs and property taxes catch many new owners off guard.

How I help: my First-Time Buyer Checklist lists the costs in the order you'll meet them, and I compare tax bills, since some newer communities add Community Facilities District taxes. What I'm paid is written in our buyer agreement before we tour, and your offer can ask the seller to cover some or all of it. Get the checklist

“What if something's wrong with the house?”

Unexpected repairs after move-in are one of the most common regrets.

How I help: I'm not a home inspector, but on tours I note the age of the roof and AC, signs of past water and the finish work. I encourage an independent inspection, and within the 10-day inspection period we can ask the seller for repairs or a credit.

“What if I feel rushed into the wrong choice?”

Many first-time buyers say they felt pressured to buy sooner than they wanted, often from worry that the economy could get worse.

How I help: no pressure from me. We compare homes side by side, I explain why each term of your offer is there, and the decision is yours. If a home isn't right, we keep looking.

“Will I even qualify?”

In a 2026 survey, only about a quarter of aspiring first-time buyers knew when to apply for a mortgage, and many aren't sure where they stand.

How I help: my kit's Lender Pre-Qualification Checklist shows which documents to gather, so you're ready to meet a lender before we tour. I'm a real estate agent, not a lender, so I'm glad to share several lenders' names, and the choice is always yours.

“Is now the right time?”

Headlines about the economy push some buyers to rush and others to wait.

How I help: I can't predict rates or prices, and I won't pretend to. I'll share dated local numbers and help you decide by your own readiness: your budget, your savings and the life you want in your home. See the current market

Worries drawn from national surveys of recent, first-time and aspiring buyers, 2025–2026: NAR 2025 Profile of Home Buyers and Sellers (Nov 2025); Bankrate (2025); Realtor.com (Nov 2025); NerdWallet and The Harris Poll (Jan 2026); Best Interest Financial and Clever Real Estate (Mar 2026); Ipsos for Wells Fargo (June 2026); FICO and The Harris Poll (July 2026). General information only, not legal or financial advice.
Tools for your first purchase

Start with your own numbers


A calm place to begin, well before you tour a single home. Nothing you type in the calculators leaves the page.

How much home?

A comfortable price range for your income, debts and savings.

Try the affordability calculator

The full monthly cost

A home's monthly payment with East Valley property taxes and insurance built in.

Try the payment calculator

How I help buyers

My buying process, buyer agreements explained clearly and new build or resale, side by side.

Buying with me
Three checklists

Get the First-Time Buyer Kit

A first-time buyer checklist, a lender pre-qualification checklist and a step-by-step homebuying timeline. All three open right away.

  • The costs to plan for, in the order you'll meet them
  • The documents your lender will ask for
  • The homebuying timeline and your key dates

Your guide opens right away, and I'll follow up personally. I never sell your information or share it for anyone else's marketing. Privacy

Your first purchase, step by step

From first sit‑down to your keys

Here is the typical path for a financed resale home on Arizona's standard purchase contract, with the dates you'll have in writing.

  1. A sit-down consultation

    We meet in person, at a time that suits you within office hours, and talk through your goals, budget, timing and every question on your list. No pressure and no obligation.

  2. Your buyer agreement

    Before we tour homes together, in person or virtually, we sign a written buyer agreement. It spells out my services, how long it lasts and what I'm paid, as a specific amount that's negotiable. I'll send it ahead so you can read it at home, and we'll go through every line before you sign. How buyer agreements work

  3. Pre-qualification with a lender

    A licensed lender reviews your finances and completes Arizona's Pre-Qualification Form for your offer. Bring the Lender Pre-Qualification Checklist from your kit so your documents are ready, and ask about loan options, down payment assistance and any homebuyer education course your program requires. Until closing, hold off on new credit cards, car loans or big purchases.

  4. Touring homes

    We tour, compare and narrow your list. It's normal for your must-haves to shift once you see homes in person, and after each tour I'll help you sort what you loved from what you could change later.

  5. Your offer and earnest money

    I study recent nearby sales, and we shape your offer together: price, timing, and any repairs or credits toward closing costs. Once it's accepted, your earnest money goes to escrow, and your lender receives the property details within 3 days. From here, Alyssa Fitting, my transaction coordinator, keeps every deadline and document on track, and you'll still hear from me for every decision.

  6. The 10-day inspection period

    You choose and hire an independent home inspector (I'm glad to share several names), plus a termite inspection, and a pool or sewer-line inspection when it applies. The seller's disclosures arrive in the first few days. Before the 10 days end, we send one written request for repairs or a credit, and you can cancel within this window and get your earnest money back.

  7. HOA documents, appraisal and loan

    If there's an HOA, its disclosure package arrives during escrow, and we read the rules and fees together. Within 10 days, a Loan Status Update from your lender goes to the seller. If the home appraises below the price, you have 5 days after you're notified to cancel and get your earnest money back. Your loan must be approved at least 3 days before closing.

  8. Final walkthrough, signing and keys

    Your Closing Disclosure arrives at least 3 business days before closing, and we review it together. After a final walkthrough, you sign with escrow, and the keys are yours once the deed records. A financed purchase typically closes 30 to 45 days after acceptance.

  9. After you move in

    Keep a cushion for upkeep and repairs, since some costs, like property taxes and insurance, can rise over time. When you need a handyman, an AC technician or a landscaper, I'm glad to share names I trust. I'm still a call away.

Timing follows the standard Arizona resale purchase contract from the Arizona Association of REALTORS®, and it can change by agreement. Your signed contract governs. Closing Disclosure timing: Consumer Financial Protection Bureau. General information only, not legal or financial advice.
Words you'll hear

  • Earnest money. Your good-faith deposit, held by escrow and credited to you at closing.
  • Escrow. The neutral company that holds the money and documents until closing.
  • SPDS. The Seller's Property Disclosure Statement: what the seller knows about the home's history and condition.
  • BINSR. The Buyer's Inspection Notice and Seller's Response, your written request for repairs or a credit. The seller has 5 days to reply.
  • LSU. The Loan Status Update, your lender's progress report to the seller.
  • CC&Rs. The HOA's rules for the community, from landscaping to parking.
  • COE. Close of escrow: the deed records with the county, and the home is yours.
  • Calendar days. Arizona contract deadlines count weekends and holidays.

From one first-time buyer to another

“New chapters are scary but exciting, and I want to be there for both.”

Brittany Fanelli, REALTOR®
Programs and resources

Help for first-time buyers in Arizona

Programs and official resources worth knowing about. Each program sets its own rules, income and credit limits and funding, and they change, so a participating lender confirms what fits you. Many ask you to finish a homebuyer education course before closing, so it helps to start early.

Down payment help to ask your lender about


Statewide

Home Plus

Down payment and closing cost help from the Arizona Industrial Development Authority, in every Arizona county. You apply through an approved Home Plus lender, not directly, and one borrower completes a homebuyer education course before closing.

Status: offered year-round, per the program's site, checked Oct 16, 2026. Home Plus at homeplusaz.com
Maricopa County

Home in Five Advantage

Down payment and closing cost help for homes in Maricopa County, offered through approved lenders. It requires a homebuyer education course with an Arizona‑based, HUD‑approved housing counseling agency.

Status: not stated on the program's site, so ask a participating lender. Checked Oct 16, 2026. homein5advantage.com
Outside Maricopa and Pima

Arizona Is Home

A first-time buyer program from the Arizona Department of Housing and the Arizona Industrial Development Authority. It isn't offered in Maricopa or Pima counties or Chino Valley, so it can apply to homes in Pinal County, such as San Tan Valley and the Pinal County part of Queen Creek.

Status: 2026 funds are used up and the program is closed for the rest of 2026, per the program's site, checked Oct 16, 2026. Arizona Is Home at homeplusaz.com

Independent guidance, at little or no cost


HUD-approved housing counselors

Independent advice from a counselor, often at little or no cost. The Consumer Financial Protection Bureau calls a housing counselor a good resource throughout the home buying process. Call HUD at 1-800-569-4287 to find an agency near you, and ask for pre-purchase counseling.

CFPB, “Get your money situation in order”; Find a housing counselor (CFPB). Checked Oct 16, 2026

The CFPB's homebuying guide

Four steps, from preparing to shop to getting ready to close, with checklists and explainers for your Loan Estimate and Closing Disclosure. Within 3 business days of your loan application, your lender must also give you the CFPB's booklet, Your Home Loan Toolkit. It's worth reading.

consumerfinance.gov/owning-a-home; Regulation Z, 12 CFR 1026.19(g). Checked Oct 16, 2026

Homebuyer education courses

Freddie Mac's CreditSmart and Fannie Mae's HomeView are online courses offered at no cost, each with a certificate when you finish. Before you start, ask your lender which course your loan or assistance program accepts. Home in Five Advantage, for one, requires an 8-hour course with an Arizona-based, HUD-approved housing counseling agency.

Freddie Mac CreditSmart · Fannie Mae HomeView · Home in Five Advantage, checked Oct 16, 2026

Arizona's buyer checklist

The Arizona Department of Real Estate's checklist for buying a home: read the seller's disclosures and the contract deadlines, consider professional home and termite inspections, and remember that the seller's agent represents the seller.

Arizona Department of Real Estate, checked Oct 16, 2026

I share these programs for information only and don't decide who qualifies. A participating lender confirms current terms, limits and funding. General information, not financial advice.

Questions first-time buyers ask

Good questions, clear answers

Do I count as a first-time buyer?

Possibly, even if you've owned a home before. Many loan and assistance programs count you as a first-time buyer if you haven't owned a home in the past three years, though each program sets its own rules, and some don't require first-time status at all. A participating lender confirms where you stand.

Do I need to sign anything before we meet?

No. Our first consultation is simply a conversation, with no obligation. Before we tour homes together, in person or virtually, we sign a written buyer agreement, and I'll walk you through every line first. Visiting an open house on your own doesn't require one.

How much do I need to save to buy my first home?

It depends on the loan program, the home's price and any assistance you qualify for, and many buyers find they need less up front than they assumed. A licensed lender can explain your options. Plan, too, for earnest money, inspections, closing costs and any HOA fees, which my First-Time Buyer Kit lists in order, plus any part of my compensation the seller doesn't agree to cover, which our buyer agreement spells out before we tour. The calculators help you see a home's full monthly cost.

Is there help with a down payment in Arizona?

Yes. Home Plus is offered statewide, Home in Five Advantage is for homes in Maricopa County, and Arizona Is Home serves first-time buyers outside Maricopa and Pima counties, though its 2026 funds are used up. You apply through a participating lender, and most ask for a homebuyer education course before closing. See the programs

When should I talk to a lender?

Before we start touring, ideally. In Arizona, your lender completes a Pre-Qualification Form that goes with your offer. Starting early leaves time to review your credit report, correct any mistakes and ask about down payment assistance and any homebuyer course it requires. I'm glad to share the names of several lenders, and the choice is always yours.

What if the inspection finds problems?

That's what the inspection period is for. Within the 10 days, we can send the seller one written request for repairs or a credit, and the seller has 5 days to reply. You can also cancel within the inspection period and get your earnest money back. I'll help you sort the items that matter most from the small ones.

Whenever you're ready

Let's talk about your next chapter.


A relaxed, sit-down consultation, in person. No pressure and no obligation. Bring your questions, and I'll bring a plan.

Brittany Fanelli, REALTOR®|Real Broker